Corporate & tax-efficient planning · Alberta
Sterling Path Solutions. Retained earnings shouldn’t be stuck earnings.
I help incorporated business owners, professionals and families keep capital working, move corporate wealth to shareholders more efficiently, and hand it down intact. Every structure explained in plain numbers, with the risks stated up front.
15–30 minutes · No cost · No obligation
You’ll speak with Charles Gendron directly · Licensed Advisor, Alberta
1(403) 690-4788- Licensed Advisor, Alberta
- Lending through major Canadian banks
- Works alongside your accountant and lawyer
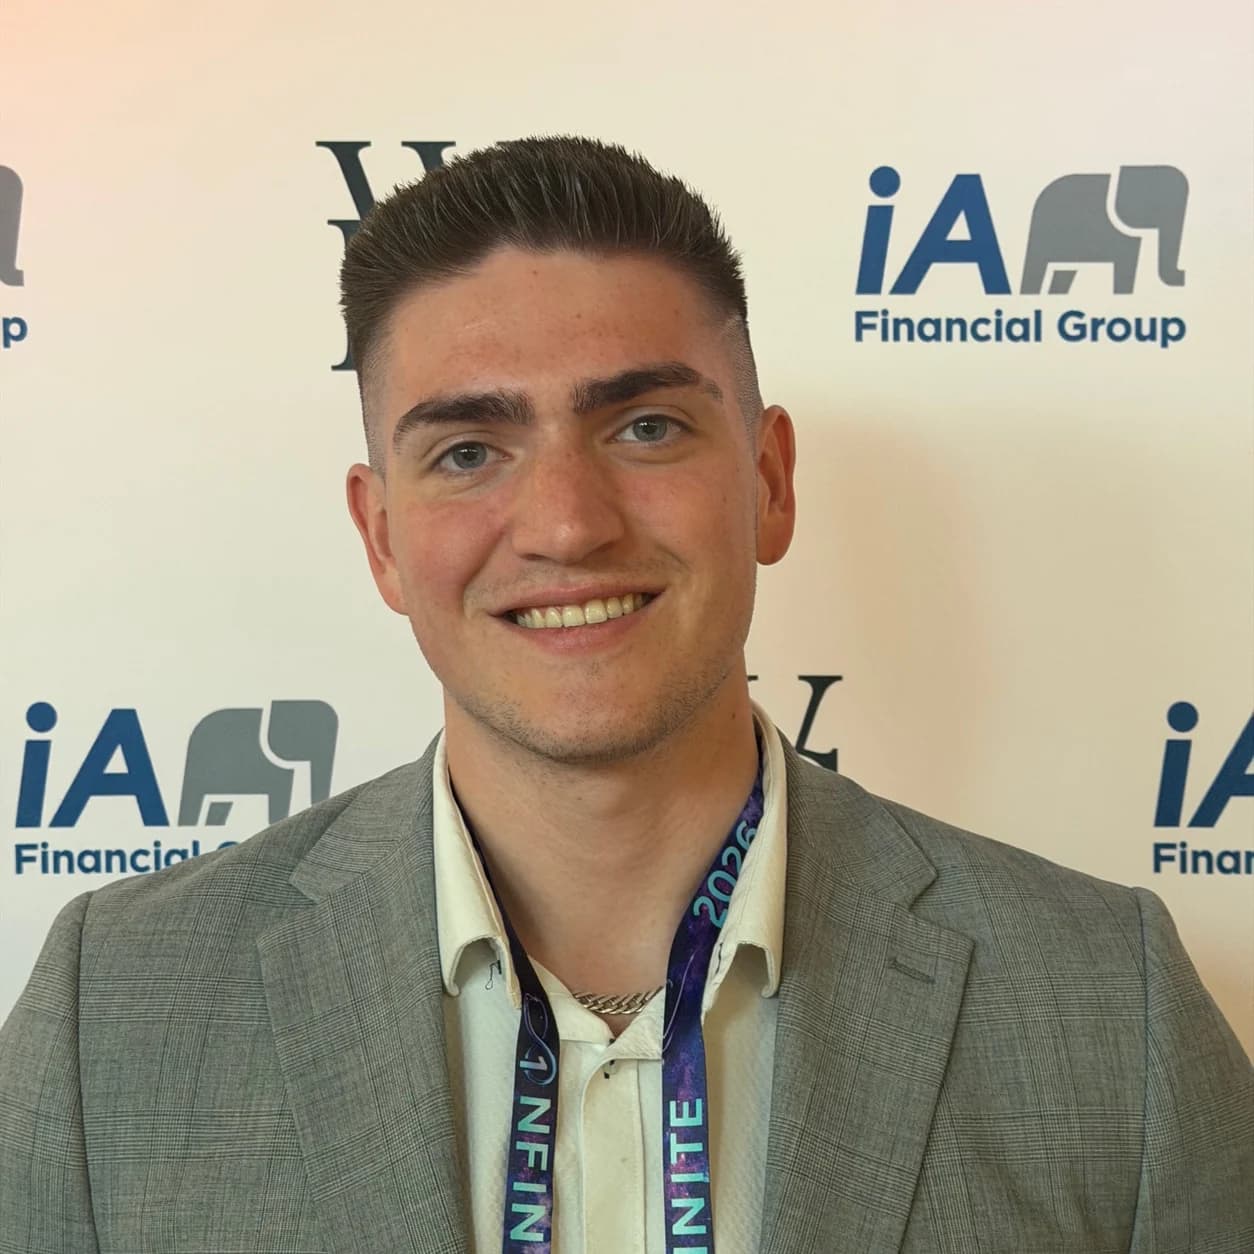
Meet the Team
Charles Gendron
Charles Gendron is a licensed agent in Alberta who helps business owners, professionals and families build the right structure around the wealth they’ve created. From keeping corporate capital working to protecting shareholders and passing wealth to the next generation, Charles explains every strategy in plain numbers and works with you for the long term.
- Licensed agent in Alberta
- Works with business owners, incorporated professionals and families
- Arranges lending and credit through major Canadian banks
- Plans alongside your accountant and lawyer
- Based in downtown Calgary: 718 8 Ave SW #400
Free discovery call
Book a Discovery Call with Charles Gendron
15–30 minutes · No cost · No obligation. Pick a time that suits you below.
718 8 Ave SW #400
Calgary, AB T2P 1H3
Everything you share stays confidential.
Charles Gendron
Licensed Advisor, Alberta
What we’ll cover
- Your business, goals and timelines
- How you’re structured today: OpCo, HoldCo, trusts
- Retained earnings and how they’re invested
- Existing coverage and shareholder agreements
- Upcoming changes: expansion, a sale, a new partner, succession
- Which strategies are worth modelling, and which aren’t
Helpful to have handy
Not required, but if they’re close by: your latest corporate financial statements, any existing life insurance policies, and your shareholders’ agreement.
Loading Charles’s calendar…
Where it leaks
Four places corporate wealth quietly leaks
Most owners we meet are doing well. Their structure just hasn’t caught up with their success. Each of these has a structural answer.
Figures are approximate 2026 Alberta combined federal–provincial rates, simplified for illustration.
$5
of small business limit lost per $1
Passive income eats your small business deduction
Every dollar of passive investment income over $50,000 a year cuts your $500,000 small business limit by $5. At $150,000 it’s gone, and in Alberta your active income is taxed at 23% instead of 11%. That’s up to $60,000 more corporate tax a year.
≈ 47%
Alberta corporate rate on investment income
Idle surplus is taxed as it earns
Interest, rent and most investment income earned inside a Canadian-controlled private corporation in Alberta is taxed at roughly 46.7% up front. Part of it is refundable later when dividends are paid, but in the meantime that money isn’t compounding for you.
≈ 42%
top personal rate on non-eligible dividends
Getting money out costs a second layer of tax
Pay yourself retained earnings as ordinary dividends and, at the top Alberta bracket, roughly 42 cents of every dollar can go to personal tax. The question is rarely whether to take money out, but which door it leaves through.
2×
the same dollar, taxed twice
Without a plan, death can tax your shares twice
At death, private company shares are treated as sold, and the value can be taxed again when the corporation pays it out. Post-mortem planning can reduce this, but it works far better when the cash and structure are set up in advance.
Small business deduction check
How much is your investment account costing your business?
Move the sliders to see how passive income inside your corporation shrinks the lower small business tax rate. It takes about twenty seconds.
Your corporation’s annual profit from operations.
Interest, dividends, rent and realized gains inside the corporation.
At a 5% return, $90,000 of passive income is roughly $1,800,000 of retained earnings invested inside the corporation.
Your small business limit
- Income losing the low rate
- $150,000
- Extra corporate tax a year
- $18,000
Over ten years, that’s about $180,000 in extra corporate tax if nothing changes.
Illustrative estimate only. Uses 2026 Alberta combined rates (11% small business, 23% general) and ignores associated corporations, the taxable-capital grind and other adjustments. Your accountant can confirm your actual position.
Bring your number to the discovery call. We’ll show you what can change it.
Immediate Financing Arrangement (IFA)
Permanent coverage, without parking your capital
An IFA lets you own permanent life insurance and borrow against it right away, so the money you’d have spent on premiums keeps working in your business or portfolio. When you die, the policy repays the loan.
Your corporation pays the premiums
It funds a participating permanent life insurance policy on a key shareholder.
Cash value builds inside the policy
Growth accumulates on a tax-sheltered basis and generally isn’t counted as passive income for the small business deduction.
The policy is assigned as collateral
A major Canadian bank takes the policy (and sometimes other assets) as security.
The bank lends the capital back
Usually each year, roughly matching the premium. It goes straight back to work in your business or investments.
At death, the death benefit repays the loan
The corporation generally receives the death benefit tax-free and the lender is repaid first.
The balance reaches shareholders
The amount above the policy’s adjusted cost basis is generally credited to the Capital Dividend Account and can be paid out as tax-free capital dividends.
What it can do for you
Your capital stays working
Hold permanent coverage without pulling money out of your business or portfolio. The premium goes in, and a loan brings the capital back out.
Tax-efficient access to cash
Borrowing against a policy isn’t a taxable withdrawal. When the loan earns business or investment income, the interest may be deductible under the Income Tax Act (Canada).
Tax-sheltered growth
Growth inside an exempt policy is sheltered and generally doesn’t count as passive income, so it doesn’t erode your small business deduction.
Liquidity for the business
The same structure can fund buy-sell agreements, protect key people, retire corporate debt and support long-term continuity.
A cleaner way to pass it on
At death, the corporation generally receives the benefit tax-free, and much of it can reach shareholders as tax-free capital dividends through the CDA.
What can go wrong
Interest rates can rise
Loan interest is usually variable. Higher rates raise your yearly cost, and the interest has to be paid from cash flow while you’re alive.
The lender can ask for more
If policy values or rates move against you, the bank may require additional collateral or, in some cases, call the loan.
Policy dividends aren’t guaranteed
Cash value growth on a participating policy depends on the insurer’s dividend scale, which can go down as well as up.
Tax rules can change
Interest deductibility, the collateral insurance deduction and CDA treatment all depend on current law, which the government can amend.
It isn’t for everyone
It suits insurable, higher-net-worth people and profitable corporations with a long horizon and genuine comfort with leverage.
Illustrative example only
The same premium, two ways to pay it
An Alberta corporation insuring a 45-year-old non-smoking shareholder. The death benefit is the same; the difference is where $1,000,000 of capital spends the next four decades.
| Pay from cash flow | Immediate Financing Arrangement | |
|---|---|---|
| Annual premium | Pay from cash flow$100,000 × 10 years | IFA$100,000 × 10 years |
| Corporate capital tied up after 10 years | Pay from cash flow$1,000,000 | IFA≈ $0 |
| Capital still working in the business | Pay from cash flow— | IFAUp to $1,000,000 |
| Loan interest in year 10 (at 6%) | Pay from cash flow— | IFA≈ $60,000, may be deductible |
| Death benefit (illustrative, age 85) | Pay from cash flow$3,500,000 | IFA$3,500,000 |
| Loan repaid from death benefit | Pay from cash flow— | IFA$1,000,000 |
| Net to the corporation | Pay from cash flow$3,500,000 | IFA≈ $2,500,000 + 40 years of returns on $1M |
Illustrative example only, not a quote or a promise of results. Assumes a participating whole life policy, a lender advancing an amount equal to each premium against the policy (additional collateral may be required), interest paid annually at 6% (actual rates vary and can change), and current tax law. Death benefit, dividends and cash values are not guaranteed and depend on the carrier’s dividend scale. Your own figures would come from a carrier illustration and a lender term sheet.
Want to see your own numbers side by side?
15–30 minutes · No cost · No obligation
The rest of the structure
One plan for the business, the shareholders and the family
An IFA is one stone in the arch. Here’s the rest of what we set up, usually alongside your accountant and lawyer.
Most plans start with one question, like how to get money out of the company, and end up touching all three: the corporation, the owners and the next generation.
Retained earnings that work harder
Surplus cash sitting in your corporation’s investment account can erode your small business deduction and is taxed heavily as it earns. We look at moving part of it into structures that may grow on a tax-sheltered basis and can reach shareholders more efficiently later.
- Passive income grind review
- Capital Dividend Account (CDA) planning
- Corporate-owned permanent insurance
Corporate Universal Life
A permanent policy owned by your corporation, with lifelong coverage and a flexible investment component inside it. Structured properly, it can grow corporate surplus on a tax-sheltered basis and create a tax-efficient transfer to shareholders or beneficiaries.
- Flexible deposits
- Choice of investment accounts inside the policy
- Higher growth potential, less guaranteed
Corporate Whole Life
Permanent coverage with guaranteed cash value that builds every year, plus the potential for policy dividends on participating plans. A steady, structured corporate asset for owners who value certainty over flexibility.
- Guaranteed cash value
- Participating dividends (not guaranteed)
- Strong collateral for lending
Estate planning and trusts
Working with your lawyer and accountant, we help set up holding companies, estate freezes and trusts, and fund the tax that’s triggered at death, so shares, land and savings pass to the next generation without a forced sale.
- Estate freeze and family trust funding
- Estate equalization between children
- Liquidity for taxes at death
Lending and credit through major Canadian banks
When you’re ready to reinvest or buy a major asset, we help arrange lending and credit through major Canadian banks, often using policy cash value as collateral so you don’t have to drain operating capital.
- Reinvestment and expansion
- Equipment, property and major assets
- Collateral structuring
Investment portfolios
Portfolios for individuals, families and corporations, set up with major Canadian banks and built around your timelines, your tax picture and the rest of your structure.
- Personal, family and corporate accounts
- Tax-aware asset location
- Coordinated with your insurance plan
Corporate UL, Whole Life or an IFA?
A plain comparison. The right answer depends on your cash flow, your horizon and how much certainty you want.
| Feature | Corporate UL | Corporate WL | IFA |
|---|---|---|---|
| Coverage | Corporate ULPermanent | Corporate WLPermanent | IFAPermanent |
| Cash value growth | Corporate ULTied to chosen investment accounts | Corporate WLGuaranteed, plus non-guaranteed dividends | IFAUsually a participating whole life policy |
| Deposit flexibility | Corporate ULHigh | Corporate WLLow: fixed premiums | IFAFixed premiums, borrowed back |
| Capital tied up | Corporate ULDeposits stay in the policy | Corporate WLPremiums stay in the policy | IFALargely returned via a loan |
| Best suited to | Corporate ULOwners wanting growth potential and flexibility | Corporate WLOwners who value guarantees and certainty | IFAInsurable owners comfortable with leverage |
Who you’ll work with
I work for people who built something
I’m Charles Gendron, a licensed advisor in Alberta. My clients are business owners, incorporated professionals, and the families behind them.
Most of them came to me with a corporation that had grown faster than its plan. Retained earnings were piling up and getting taxed, a partner agreement had never been funded, or the family had no clear path for passing the business on. My job is to find the piece that holds everything else together, and set it properly.
I work with corporations of every size, from start-ups to established holding companies, and with individuals and families on estate planning, trusts and death benefit planning, so the wealth you build can reach your shareholders, family and estate as efficiently as the rules allow.
“Your finances have a keystone. Take it out and the rest comes down. Put it in properly and it holds for generations.”
Why owners stay
You deal with me, directly
Not a call centre, not a rotating junior. I’m on the first call and I stay on the file, backed by a capable team.
Mechanics first, risks included
You’ll see how every structure works on paper, what it costs, and what could go wrong, before you decide anything.
Built with your accountant and lawyer
I bring the numbers and the insurance and lending pieces. Your professionals keep their seat at the table.
Measured in decades
The plans we set up are meant to be reviewed as your business, family and tax rules change, for as long as you need them.
Industries I know from the inside
Every industry has its own rhythm: seasonal cash flow on the farm, equipment-heavy balance sheets in excavation, professional corporation rules for physicians and dentists. I plan around yours.
- Medical practices
- Dental practices
- Law firms
- Oil and gas services
- Construction
- Drilling and excavation
- Mining
- HVAC and trades
- Farming and agriculture
- Real estate
- Property management
- Asset management
- Technology and IT
- Family-owned businesses
- Holding companies
- Start-ups and founders
Structures in practice
What a finished structure looks like
Four composite scenarios based on situations we see often across Alberta. Pick the one closest to yours.
Professional corporation · Calgary area
$1.4 million in the corporate account, and the tax bill creeping up
A dentist in her late forties has built up $1.4M of retained earnings inside her professional corporation, mostly in a taxable investment account earning about $70,000 a year. That passive income is quietly shrinking her small business deduction.
The structure
- Moved part of the surplus into a corporate-owned participating whole life policy over several years
- Kept an emergency reserve and practice-expansion fund fully liquid
- Coordinated with her accountant to track the Capital Dividend Account
- Passive income before
- $70,000/yr
- Small business limit lost
- $100,000
- Est. corporate tax saved
- ≈ $12,000/yr
The result: With passive income brought back under the $50,000 threshold, the full small business limit may be restored, while the policy’s cash value grows on a tax-sheltered basis and the eventual death benefit can flow out largely through the CDA.
Excavation contractor · Edmonton region
Two partners, a $6 million company and a buy-sell nobody had funded
Two 50/50 shareholders have a shareholders’ agreement with a buy-sell clause, but no money behind it. If one died, the survivor would owe the family roughly $3M, with most of the value tied up in equipment and contracts.
The structure
- Corporate-owned permanent coverage on each shareholder, sized to the agreement
- Agreement reviewed by their lawyer so the insurance proceeds and CDA credit flow as intended
- Scheduled valuation review every two years
- Buy-out obligation
- $3,000,000 each
- Funded by
- Tax-free death benefit¹
- Equipment sold to fund it
- None
The result: If either partner dies, the corporation receives the death benefit, can redeem the shares, and may pay the family through the Capital Dividend Account. The survivor keeps the company; the family receives fair value.
Grain operation · Central Alberta
One child farming, two who aren’t, and land nobody wants to sell
Parents in their sixties own a grain operation worth about $8M, most of it land. One child farms with them; two have careers in the city. They want the farm kept whole and the children treated fairly.
The structure
- Estate freeze and family trust set up with their lawyer and accountant
- Joint last-to-die permanent coverage to create value for the non-farming children
- Liquidity planned for taxes arising on the second death
- Farm transferred to
- The farming child
- Policy proceeds for siblings
- ≈ $2.5M each
- Land sold to pay tax
- None planned
The result: The farming child inherits the operation intact; the siblings receive fair value from the policy and other estate assets; the estate has cash for the tax bill instead of a forced sale of land.
Software company · Calgary
A founder who needed coverage but refused to park $150,000 a year
A 42-year-old founder wants permanent coverage for his holding company and family, but every spare dollar is earmarked for growth. Paying $150,000 a year in premiums out of working capital was a non-starter.
The structure
- Immediate Financing Arrangement: HoldCo funds a participating policy each year
- The policy is assigned to a major Canadian bank, which lends the premium back
- Borrowed funds reinvested in the operating business
- Annual premium
- $150,000 × 10 yrs
- Capital kept working
- Up to $1.5M
- Interest
- May be deductible²
The result: The founder keeps his capital in the business, holds permanent coverage, and the loan is designed to be repaid from the death benefit — with the balance potentially flowing to his family through the CDA.
Illustrative composite scenarios, not specific clients. Details are representative; figures are simplified and rounded. Outcomes depend on individual circumstances, insurability, carrier illustrations, lender terms and current tax law.
¹ Life insurance death benefits are generally received tax-free by the beneficiary. ² Interest may be deductible when borrowed funds are used to earn business or property income, subject to conditions under the Income Tax Act (Canada).
See yourself in one of these? That’s exactly what the first call is for.
How we start
Three steps, and the first one is free
- 1
A 15–30 minute discovery call
We talk through your business, your goals, how you’re structured today, the coverage you already have, and anything coming up: a sale, a new partner, an expansion, a succession.
Free, confidential, no obligation.
- 2
Your structure, mapped and modelled
We lay out the corporate, personal and family pieces on one page, model the options with real numbers, and review them with your accountant and lawyer.
Plain-language summary, risks included.
- 3
Set in place, then kept current
We implement with the insurance carriers and lenders, then review the plan as your business, family and tax rules change over the years.
Reviewed as your life changes.
Talk it through with Charles
Licensed Advisor, Alberta · 1(403) 690-4788
15–30 minutes · No cost · No obligation
Straight answers
Questions owners ask first
Don’t see yours? Send it over and Charles will answer it personally.
Your corporation (or you) buys a permanent life insurance policy, then assigns that policy to a lender as collateral and borrows back money to reinvest in your business or investments. You end up with permanent coverage and most of your capital still working. When the insured person dies, the death benefit repays the loan and the balance goes to the corporation or beneficiaries.
It’s generally not suitable if you’re not comfortable borrowing, if your cash flow can’t handle interest costs rising, if you can’t qualify medically for coverage, or if you don’t have a long-term need for permanent insurance. It’s designed for higher-net-worth, insurable people and profitable corporations with a long horizon.
It may be. Interest is generally deductible when borrowed money is used to earn income from a business or property, and a portion of the policy cost may also be deductible as a collateral insurance expense. Both are subject to conditions under the Income Tax Act (Canada). Your accountant should confirm how the rules apply to you.
One of the main tools is the Capital Dividend Account. When a corporation receives a life insurance death benefit, the amount above the policy’s adjusted cost basis is generally credited to the CDA, and capital dividends paid from it can generally be received by Canadian-resident shareholders tax-free. Timing, elections and structure matter, which is why we plan it with your accountant.
It’s 15 to 30 minutes with Charles. We talk about your business, your goals, how you’re set up today, any coverage you already have, and what’s changing in the next few years. You leave with a clear view of what’s worth exploring. There’s no cost, no obligation and no hard sell.
Yes, and we prefer to. Corporate insurance, estate freezes and trusts work best when your accountant and lawyer are part of the design. We share the numbers, answer their questions and make sure every piece fits your existing structure.
The discovery call is free. When we put an insurance solution in place, advisors are typically compensated by the insurance carrier. We’ll explain exactly how compensation works for any recommendation before you commit to anything.
Yes. Charles is licensed in Alberta and works with business owners, professionals and families across the province, from our office in downtown Calgary or by phone and video. If you’ve recently moved out of Alberta, ask us and we’ll point you in the right direction.
Let’s find your keystone
One conversation is usually enough to see whether your structure is working as hard as you are. If it is, I’ll tell you.
15–30 minutes · No cost · No obligation
Charles Gendron
Licensed Advisor, Alberta
On the call we’ll cover
- Where your retained earnings sit today, and what they’re costing you
- Whether an IFA or corporate policy fits your cash flow
- Gaps in shareholder, key-person or estate protection
- Clear next steps, whether or not we work together